Mortgage Refinance Rates in India: Home Loan Balance Transfer Rates
Home loan refinance (balance transfer) rates at 12 Indian lenders start between 7.15% and 8.50% as of 17 September 2026.
Written by Vikram Desai
Updated on 17 September 2026·6 min read
On this page7 sections
In India, mortgage refinancing is done through a home loan balance transfer, where a new lender pays off your existing loan. Floating refinance rates at the 12 lenders we track start between 7.15% and 8.50% a year, as of 17 September 2026. Switching from 9.00% to 8.00% on ₹40 lakh with 15 years left cuts the EMI by ₹2,345 and saves about ₹4.22 lakh in interest.
Key facts
| Item | Position on 17 September 2026 |
|---|---|
| What refinancing is called in India | Home loan balance transfer or takeover |
| Lowest starting rate we track | 7.15% (Canara Bank, LIC Housing Finance, Union Bank of India) |
| RBI policy repo rate | 5.25%; next policy meeting 5–7 October 2026 |
| Reset on repo-linked loans | At least once every three months |
| Foreclosure charge, floating-rate home loan to an individual | Nil |
| Processing fee at the new lender | From 0.25% to 3% of the loan, often with caps, plus GST |
Home loan refinance rates by lender
Updated 17 Sep 2026 · Lender rate pages, checked individually. These are advertised floating rates. The rate you get depends on your credit score, income, loan size and property.
| Lender | Type | Floating rate | Processing fee | Benchmark |
|---|---|---|---|---|
| Canara Bank | Public sector bank | 7.15% – 10.00% | 0.50%, min ₹1,500, max ₹10,000 + GST | Repo-linked (RLLR) |
| LIC Housing Finance | Housing finance company | 7.15% – 10.15% | Up to 0.25% | LHPLR-linked |
| Union Bank of India | Public sector bank | 7.15% – 9.35% | 0.50%, max ₹15,000 + GST | Repo-linked (EBLR) |
| Bank of Baroda | Public sector bank | 7.20% – 8.95% | 0.50% (₹8,500–₹15,000) up to ₹50 lakh; 0.25% (₹8,500–₹25,000) above | Repo-linked (EBLR) |
| Bajaj Housing Finance | Housing finance company | 7.25% – 10.25% | Up to 1% | BHFL floating reference rate |
| Punjab National Bank | Public sector bank | 7.25% – 9.15% | 0.35%, min ₹2,500, max ₹15,000 | Repo-linked (RLLR) |
| State Bank of India | Public sector bank | 7.25% – 8.55% | 0.35%, min ₹5,000, max ₹15,000 + GST (salaried) | Repo-linked (EBLR) |
| Kotak Mahindra Bank | Private bank | 7.60% – 9.50% | Up to 2% + taxes | Repo-linked (EBLR) |
| HDFC Bank | Private bank | 7.75% – 13.20% | Up to 0.5%, min ₹4,000 | Repo-linked (EBLR) |
| Axis Bank | Private bank | 8.00% – 9.10% | Up to 1% or ₹10,000, whichever is higher, + GST | Repo-linked (EBLR) |
| Tata Capital Housing | Housing finance company | 8.00% – 13.00% | Up to 3% + GST | PLR-linked |
| ICICI Bank | Private bank | 8.50% – 9.65% | 0.5% + taxes | Repo-linked (EBLR) |
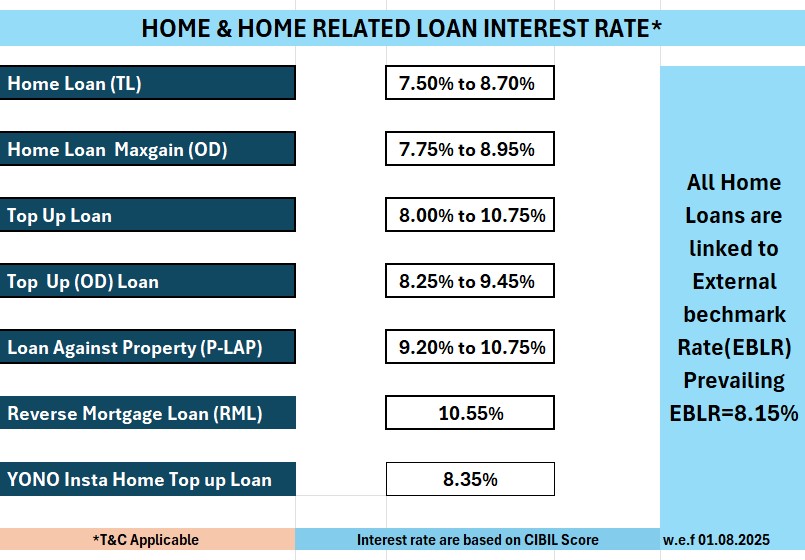
Most lenders quote the same rate card for a takeover as for a new home loan, but some price transfers separately. Ask for the takeover rate in writing. Our home loan interest rates page tracks these lenders as their cards change.
When refinancing your home loan pays off
Compare what you save in interest against what the switch costs. The example below uses ₹40 lakh outstanding and 15 years left.
| Rate | Monthly EMI | Total interest over 15 years |
|---|---|---|
| 9.00% (current loan) | ₹40,571 | ₹33,02,719 |
| 8.00% (after refinance) | ₹38,226 | ₹28,80,695 |
| 7.25% (after refinance) | ₹36,515 | ₹25,72,613 |
A one-point cut saves ₹4,22,024 in interest. At SBI’s 0.35% fee, capped at ₹15,000, the processing charge on ₹40 lakh is ₹14,000 plus GST. Legal, valuation and stamp duty on the new mortgage add to that, and these vary by lender and state.
| Item | Details |
|---|---|
| Switch early | the savings are largest when many years are left, because interest is front-loaded. |
| Ask your bank first | your current lender may offer a lower rate for a conversion fee. Compare that fee with the full cost of moving. |
| Keep the tenure | a transfer resets the loan, so do not stretch the term unless you mean to. |
Run your own numbers in the balance transfer savings calculator.
How to refinance a home loan in India
- Get a statement of the outstanding principal and a list of documents held from your current lender.
- Check your credit report and fix any errors before you apply.
- Apply to the new lender for a balance transfer with KYC, income proof, the property papers and your loan account statement.
- Read the Key Facts Statement and sanction letter for the rate, benchmark, spread, fees and reset date.
- Ask your current lender for a foreclosure letter giving the exact payoff amount.
- The new lender pays the old lender directly. Collect your original property documents and a no-dues certificate from the old lender.
- Sign the new loan agreement and mortgage documents, and check that the old loan shows as closed on your credit report.
For eligibility and document lists by lender, see our home loan balance transfer guide.
Rules that protect you when you switch
| Item | Details |
|---|---|
| No foreclosure penalty | since 2014 RBI has barred banks from charging foreclosure or prepayment penalties on floating-rate term loans to individual borrowers. |
| 2026 rules | the RBI (Pre-payment Charges on Loans) Directions, 2025 apply to loans sanctioned or renewed from 1 January 2026. Lenders cannot charge for part or full prepayment of a floating-rate loan taken by an individual for non-business use. There is no lock-in, and it does not matter where the money comes from. |
| Rate resets | loans linked to an external benchmark such as the repo rate must be reset at least once every three months. |
| Disclosure | any prepayment charge must be stated in the sanction letter, loan agreement and Key Facts Statement. |
If a lender refuses to release documents or charges a fee it should not, complain to the lender first. After 30 days, or after an unsatisfactory reply, you can go to the RBI Ombudsman at cms.rbi.org.in under the Integrated Ombudsman Scheme, 2026, within 90 days.
Frequently asked questions
What are mortgage refinance rates in India?
They are the rates a new lender charges to take over your home loan. At the 12 lenders we track, floating rates start between 7.15% and 8.50% as of 17 September 2026.
How does mortgage loan refinancing work in India?
You apply for a balance transfer, the new lender pays off your old loan, and you repay the new lender at its rate. Your property documents move to the new lender.
Is there a penalty to refinance a floating-rate home loan?
No. Banks cannot charge foreclosure penalties on floating-rate term loans to individuals, and the 2026 Directions extend this to all regulated lenders for non-business loans.
How much lower should the new rate be?
There is no fixed rule. Work out the interest saved over the remaining tenure and subtract fees, legal and stamp duty costs. A cut of one percentage point on ₹40 lakh over 15 years saves about ₹4.22 lakh.
Can I refinance an education loan in India?
Yes, some banks take over education loans. SBI, for example, runs a Take-over of Education Loans scheme. Compare current rates on our education loan interest rates page.
Will refinance rates fall after the October 2026 RBI policy?
Nobody can say in advance. The repo rate is 5.25%, and the next decision is due after the 5–7 October 2026 meeting. Repo-linked loans pass on any change at their next reset.
Sources
- Retail lending rates linked to RLLR — Canara Bank (checked 17 Sep 2026)
- Home loan — LIC Housing Finance (checked 17 Sep 2026)
- Retail rates of interest — Union Bank of India (checked 17 Sep 2026)
- Retail loan interest rates — Bank of Baroda (checked 17 Sep 2026)
- Home loan interest rates — Bajaj Housing Finance (checked 17 Sep 2026)
- Retail advances interest rates — Punjab National Bank (checked 17 Sep 2026)
- Home loan rates of interest — State Bank of India (checked 17 Sep 2026)
- Home loan interest rates — Kotak Mahindra Bank (checked 17 Sep 2026)
- Home loan interest rates — HDFC Bank (checked 17 Sep 2026)
- Home loan interest rates and charges — Axis Bank (checked 17 Sep 2026)
- Home loan rates and charges — Tata Capital (checked 17 Sep 2026)
- Home loan interest rates — ICICI Bank (checked 17 Sep 2026)
- Reserve Bank of India (Pre-payment Charges on Loans) Directions, 2025 — RBI (checked 17 Sep 2026)
- Levy of foreclosure charges on floating rate term loans, 7 May 2014 — RBI (checked 17 Sep 2026)
- External benchmark based lending, 4 September 2019 — RBI (checked 17 Sep 2026)
- Reserve Bank – Integrated Ombudsman Scheme, 2026 FAQs — RBI (checked 17 Sep 2026)
- Take-over of Education Loans — State Bank of India (checked 17 Sep 2026)
Compare loans with live numbers
Compare interest rates, processing fees and eligibility across every lender in India — home loans, personal loans, gold loans, car loans, education loans and business credit. All-in cost, not just the teaser rate.
Related articles
-
RBI Raises Repo Rate to 5.50 Per Cent in Policy Stance Shift
The Reserve Bank of India raised the repo rate by 25 basis points to 5.50 per cent and adopted a…
-
RBI Raises Policy Repo Rate to 5.50% and Shifts Stance
The Reserve Bank of India has raised the policy repo rate by 25 basis points to 5.50 per cent and…
-
RBI Raises Policy Repo Rate to 5.50 Per Cent
The Reserve Bank of India raised the policy repo rate by 25 basis points to 5.50 per cent on…
-
RBI Increases Repo Rate to 5.50 Per Cent in October 2026
The Reserve Bank of India increased the policy repo rate by 25 basis points to 5.50 per cent during…