Home Loan EMI Calculator with Repayment Schedule
₹50 lakh at 7.25% for 20 years costs ₹39,519 a month; the repayment schedule shows interest exceeds principal until year 11.
Written by Priya Nair
Updated on 17 September 2026·5 min read
On this page8 sections
A home loan EMI calculator with a repayment schedule shows your fixed monthly EMI and how each payment splits into interest and principal over the tenure. On a ₹50 lakh loan at 7.25% for 20 years, the EMI is ₹39,519, and ₹30,208 of the first EMI is interest. Principal overtakes interest only in year 11.
Key facts
| Item | Figure |
|---|---|
| EMI formula | EMI = P × r × (1 + r)^n ÷ [(1 + r)^n − 1] |
| Example loan | ₹50,00,000 at 7.25% for 20 years (240 EMIs) |
| EMI | ₹39,519 a month |
| Total interest | ₹44,84,512 |
| Total repaid | ₹94,84,512 |
| Half the principal repaid | After about 161 EMIs (13 years 5 months) |
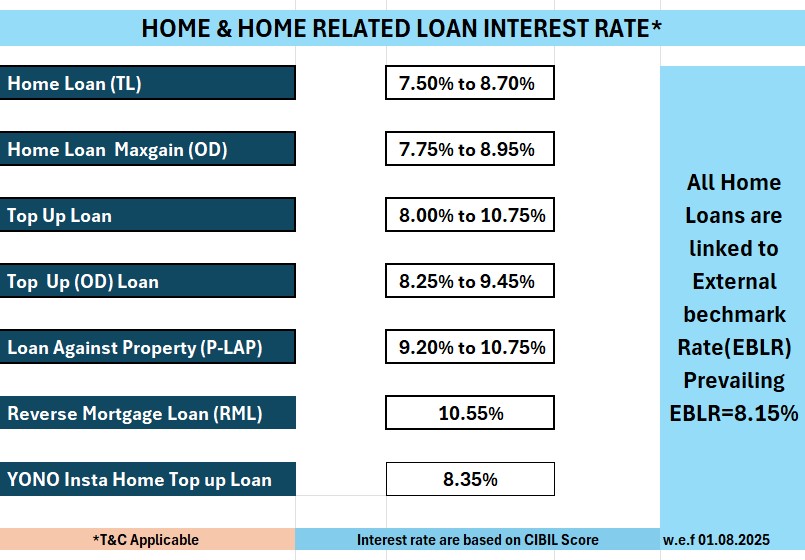
| Starting home loan rates, 12 lenders we track | 7.15% to 8.50% (checked 17 Sep 2026) |
| RBI repo rate | 5.25%; next policy decision after the 5–7 October 2026 meeting |
Updated 17 Sep 2026 · Lender rate pages, checked individually. The 7.25% example is the advertised starting rate at SBI, PNB and Bajaj Housing Finance; your rate depends on your credit score and loan size.
How to calculate home loan EMI
In the formula, P is the loan amount, r is the monthly rate (annual rate ÷ 12 ÷ 100) and n is the number of monthly instalments. Banks use the reducing-balance method, so interest each month is charged only on the principal still outstanding.
- Convert the rate: 7.25 ÷ 12 ÷ 100 = 0.006042.
- Convert the tenure: 20 years × 12 = 240 months.
- Put the values in the formula: ₹50,00,000 × 0.006042 × (1.006042)^240 ÷ [(1.006042)^240 − 1] = ₹39,519.
- For month 1, interest = ₹50,00,000 × 0.006042 = ₹30,208. The rest of the EMI, ₹9,310, repays principal.
- Subtract that principal from the balance and repeat each month. The list of these rows is the repayment (amortisation) schedule.
Our EMI calculator does this instantly, and the amortisation calculator prints the month-by-month schedule.
Home loan repayment schedule: year-by-year example
The table shows selected years for ₹50 lakh at 7.25% over 20 years, assuming the rate does not change.
| Year | Principal paid in the year | Interest paid in the year | Balance at year end |
|---|---|---|---|
| 1 | ₹1,15,514 | ₹3,58,712 | ₹48,84,486 |
| 2 | ₹1,24,173 | ₹3,50,053 | ₹47,60,313 |
| 5 | ₹1,54,241 | ₹3,19,984 | ₹43,29,106 |
| 10 | ₹2,21,390 | ₹2,52,835 | ₹33,66,137 |
| 11 | ₹2,37,986 | ₹2,36,240 | ₹31,28,152 |
| 15 | ₹3,17,773 | ₹1,56,453 | ₹19,83,939 |
| 20 | ₹4,56,116 | ₹18,110 | ₹0 |
After 10 years of EMIs you still owe about two-thirds of the loan. That is why a part-prepayment early in the tenure saves the most interest.
EMI per lakh for a home loan
Multiply these figures by your loan amount in lakh for a quick estimate.
| Tenure | EMI per ₹1 lakh at 7.25% | Total interest per ₹1 lakh |
|---|---|---|
| 10 years | ₹1,174 | ₹40,881 |
| 15 years | ₹913 | ₹64,315 |
| 20 years | ₹790 | ₹89,690 |
| 30 years | ₹682 | ₹1,45,583 |
At 8.50%, the starting rate at ICICI Bank, the 20-year EMI rises to ₹868 per lakh. On ₹50 lakh, stretching the tenure from 20 to 30 years cuts the EMI to ₹34,109 but raises total interest to ₹72,79,173. A 15-year term means an EMI of ₹45,643 and total interest of ₹32,15,766.
For a small loan, ₹5 lakh at 7.25% over 5 years costs ₹9,960 a month and ₹97,581 in interest. Compare current lender rates on our home loan interest rates page.
When your schedule changes
| Item | Details |
|---|---|
| Repo rate changes. | Most new floating-rate home loans are linked to the repo rate. When the rate resets, the lender changes your EMI, your tenure or both. Read how a repo rate change affects your EMI. |
| Your choice at reset. | RBI rules on floating-rate EMI loans to individuals require lenders to let you choose a higher EMI, a longer tenure or a mix, and to let you prepay at any time. |
| Quarterly statement. | Lenders must send a statement each quarter showing principal and interest recovered so far, the EMI, the number of EMIs left and the annualised rate. |
| Prepayment. | Lenders cannot charge a prepayment fee on a floating-rate loan taken by an individual for a non-business purpose. See the RBI prepayment rule and try the prepayment calculator. |
Home loan calculator with increasing EMI
A step-up (increasing EMI) plan starts with a lower EMI that rises over time, and the schedule then front-loads even more interest, so total interest is higher than on a level EMI at the same rate. Only some lenders offer it, on their own terms, so ask for the plan’s schedule before you sign.
Before you sign the loan agreement, the lender must give you a Key Facts Statement. Under RBI rules, for retail loans sanctioned from 1 October 2024, it carries the annual percentage rate and the loan’s amortisation schedule over the full tenure, so you can check the lender’s numbers against your own calculation.
Frequently asked questions
How do I get a home loan EMI schedule?
Use an amortisation calculator with your loan amount, rate and tenure, or ask your lender. The Key Facts Statement includes the amortisation schedule, and the quarterly statement shows what you have repaid so far.
What is the formula for home loan EMI calculation?
EMI = P × r × (1 + r)^n ÷ [(1 + r)^n − 1], where r is the monthly rate and n the number of months. ₹50 lakh at 7.25% for 240 months gives ₹39,519.
What is the EMI per lakh for a home loan?
At 7.25%, it is ₹790 per lakh over 20 years and ₹682 over 30 years. At 8.50% over 20 years, it is ₹868.
What is the EMI for a ₹5 lakh home loan for 5 years?
At 7.25%, the EMI is ₹9,960 and total interest is ₹97,581. The figure changes with the rate your lender offers.
Why is most of my early EMI going to interest?
Interest is charged on the outstanding balance, which is highest at the start. On a ₹50 lakh, 20-year loan at 7.25%, interest exceeds principal until year 11.
Does the repayment schedule change if the repo rate changes?
Yes, for repo-linked loans. At the next reset, the lender revises your EMI or tenure, and you can ask for the option you prefer.
Sources
- Reset of floating interest rate on EMI-based personal loans — Reserve Bank of India (checked 17 Sep 2026)
- Key Facts Statement for loans and advances — Reserve Bank of India (checked 17 Sep 2026)
- Interest Rates on Advances Directions — Reserve Bank of India (checked 17 Sep 2026)
- Pre-payment Charges on Loans Directions, 2025 — Reserve Bank of India (checked 17 Sep 2026)
- Home loan interest rates — State Bank of India (checked 17 Sep 2026)
- Retail advances interest rates — Punjab National Bank (checked 17 Sep 2026)
- Home loan interest rates — ICICI Bank (checked 17 Sep 2026)
- Rates of interest linked to RLLR — Canara Bank (checked 17 Sep 2026)
Compare loans with live numbers
Compare interest rates, processing fees and eligibility across every lender in India — home loans, personal loans, gold loans, car loans, education loans and business credit. All-in cost, not just the teaser rate.
Related articles
-
How Lenders Work Out Loan Eligibility
A loan eligibility calculator is a digital tool that estimates the maximum loan amount an…
-
Business Loan EMI Calculator: Formula, Examples and Hidden Costs
A ₹10 lakh business loan at 16% for 3 years has an EMI of ₹35,157 and total interest of ₹2,65,653.…
-
How Loan EMI Is Calculated — Rates, EMI and Eligibility
Equated Monthly Instalment (EMI) is a fixed payment made by a borrower to a lender each month,…
-
Bike Loan EMI Calculator: Two-Wheeler EMI, Rates and Down Payment
A ₹1 lakh bike loan at 12.40% over 3 years costs ₹3,341 a month. Formula, EMI tables, down payment…