What Is a Mortgage Loan? Meaning, Types and How It Works in India
A mortgage loan is a loan secured by property; Section 58 of the Transfer of Property Act, 1882 defines the mortgage and its six types.
Written by Ananya Iyer
Updated on 17 September 2026·6 min read
On this page8 sections
A mortgage loan is a loan secured by property: you pledge a house, flat or plot, and the lender can sell it if you do not repay. Section 58 of the Transfer of Property Act, 1882 defines a mortgage as the transfer of an interest in specific immovable property to secure a loan. With a typical bank loan you keep living in the property until you repay.
Mortgage loan meaning: key facts
| Term | Meaning |
|---|---|
| Mortgage | Transfer of an interest in specific immovable property to secure a loan or debt |
| Mortgagor | You, the borrower who offers the property |
| Mortgagee | The lender, such as a bank or housing finance company |
| Mortgage money | The principal and interest the property secures |
| Mortgage deed | The document that creates the mortgage, if there is one |
| Law | Sections 58 to 104, Transfer of Property Act, 1882 |
| Home loan rates, 12 lenders tracked | 7.15% to 13.20% (17 September 2026) |
| Return of property papers after full repayment | Within 30 days; ₹5,000 a day if the lender causes a delay |
How a mortgage loan works
| # | Item | Details |
|---|---|---|
| 1 | You apply. | The lender checks your income, credit score and existing loans to decide how much you can borrow. |
| 2 | The lender checks the property. | A lawyer verifies the title and a valuer puts a market value on it. |
| 3 | The loan is sized to the property. | For housing loans, RBI rules cap the loan-to-value ratio: the cap is 90% for loans up to ₹30 lakh, 80% for ₹30 lakh to ₹75 lakh, and 75% above ₹75 lakh. |
| 4 | The mortgage is created. | Many lenders use a mortgage by deposit of title deeds: you hand over the original sale deed and related papers. |
| 5 | You repay in EMIs. | Each EMI covers interest plus part of the principal. Early EMIs are mostly interest. |
| 6 | The mortgage ends. | Within 30 days of full repayment, the lender must return your original documents and remove any charge it registered with a registry. |
A term loan mortgage works the same way: a fixed sum repaid in EMIs over a set term, often 15 to 30 years for a home loan. You can estimate your EMI with our EMI calculator.
Types of mortgage under Indian law
Section 58 of the Transfer of Property Act names six types.
| Type | How it works |
|---|---|
| Simple mortgage | You keep possession and personally promise to repay. If you default, the lender can have the property sold. |
| Mortgage by conditional sale | You appear to sell the property. The sale becomes final if you default, or is undone when you repay. The condition must be in the sale document. |
| Usufructuary mortgage | The lender takes possession and keeps the rent or income in place of interest or repayment until the debt is cleared. |
| English mortgage | You transfer the property outright, and the lender must transfer it back once you repay on the agreed date. |
| Mortgage by deposit of title deeds | You deliver the title documents to the lender to create security. It is allowed in Kolkata, Chennai, Mumbai and other towns notified by the state government. |
| Anomalous mortgage | Any mortgage that does not fit the five types above. |
Section 59 says a mortgage securing ₹100 or more must be made by a registered deed, signed by you and attested by two witnesses. A mortgage by deposit of title deeds is the exception: it needs no registered mortgage deed.
Home loan and mortgage loan: the difference
Every home loan is a mortgage, because the house you buy secures it. In Indian banking, though, “mortgage loan” usually means a loan against property (LAP): you borrow against a home or shop you already own, for almost any purpose.
| Point | Home loan | Loan against property |
|---|---|---|
| Purpose | Buy, build or repair a house | Almost any purpose, including business |
| Security | The house being bought or built | A property you already own |
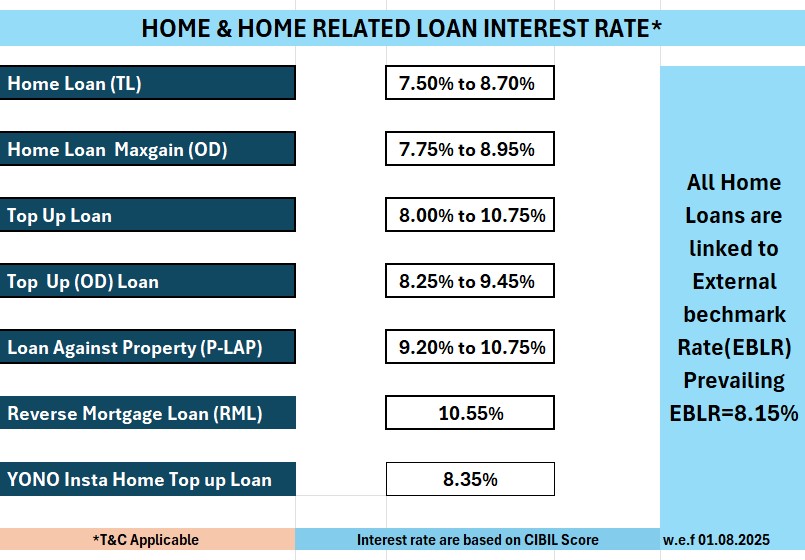
| Typical rate | Lower | Higher; SBI charges 8.95% to 10.50%, against 7.25% to 8.55% on its home loan |
For current lender-by-lender rates on both, see our guide to mortgage loan interest rates.
What a mortgage loan costs
The 12 home loan lenders we track charge 7.15% to 13.20% a year, as of 17 September 2026. Most floating rates track the RBI repo rate, which is 5.25%. The RBI’s next policy meeting runs from 5 to 7 October 2026.
On a ₹50 lakh loan over 20 years, a 7.25% rate means an EMI of ₹39,519 and total interest of ₹44,84,512. Beyond interest, budget for:
- a processing fee, often 0.35% to 1% of the loan plus GST;
- legal and valuation charges;
- stamp duty on the loan or mortgage document, which varies by state.
Lenders cannot charge a prepayment fee on a floating-rate loan taken by an individual for a non-business purpose. This applies to loans sanctioned or renewed from 1 January 2026.
What happens if you do not repay
Missed EMIs are reported to the credit bureaus, which now receive lender data on the 9th, 16th and 23rd and the last day of every month. If a loan becomes a non-performing asset, a bank can act under Section 13(2) of the SARFAESI Act, 2002. It sends a written notice giving you 60 days to repay in full. If you do not, it can take possession of the property and sell it without first filing a suit. You can challenge such action before the Debts Recovery Tribunal.
Your right to redeem the property by paying what is due is protected by Section 60 of the Transfer of Property Act, until a court decree or the parties’ own act ends it. If you are struggling, talk to your lender before the account turns bad. For a dispute about how a bank handled your loan, you can complain under the RBI Integrated Ombudsman Scheme, 2026. For complex cases, a lawyer can advise on your rights.
Frequently asked questions
What is a mortgage loan in simple words?
It is a loan where you pledge property as security. If you repay, the property stays yours with no claim on it; if you default, the lender can sell it to recover the money.
What is a mortgage loan in India?
Legally, it is any loan secured by a mortgage of immovable property under the Transfer of Property Act, 1882. In bank terms, it usually means a loan against property.
How does a mortgage loan work?
The lender values your property, lends a share of that value and holds your title documents until you repay in EMIs. After the last EMI, it must return the papers within 30 days.
What is the purpose of a mortgage loan?
A home loan mortgage pays for a house. A loan against property can fund education, medical costs, a wedding or a business, using a property you already own.
What is the term of a mortgage loan?
Home loans often run up to 30 years. Loans against property usually have shorter terms: Bank of Baroda’s standard card covers up to 10 years, and SBI’s up to 15.
Who keeps the property documents during a mortgage?
The lender keeps the original title documents. It must return them within 30 days of full repayment, at the branch that serviced the loan or another office holding them, as you prefer. If the delay is its fault, it pays you ₹5,000 a day.
Sources
- Transfer of Property Act, 1882, sections 58–60 — India Code (checked 17 Sep 2026)
- Section 13(2), SARFAESI Act, 2002 — Indian Kanoon (checked 17 Sep 2026)
- Release of movable and immovable property documents on repayment, 13 Sep 2023 — Reserve Bank of India (checked 17 Sep 2026)
- Pre-payment Charges on Loans Directions, 2025 — Reserve Bank of India (checked 17 Sep 2026)
- Master Direction for housing finance companies (LTV limits) — Reserve Bank of India (checked 17 Sep 2026)
- Monetary policy statement, August 2026 — Reserve Bank of India (checked 17 Sep 2026)
- Home and home-related loan interest rates, w.e.f. 20.05.2026 — State Bank of India (checked 17 Sep 2026)
- Home loans interest rates (current) — State Bank of India (checked 17 Sep 2026)
Compare loans with live numbers
Compare interest rates, processing fees and eligibility across every lender in India — home loans, personal loans, gold loans, car loans, education loans and business credit. All-in cost, not just the teaser rate.
Related articles
-
What a Mortgage Is, and How It Differs From a Home Loan
Unlock your dream home! Understand Indian mortgages in 2026, from definition to types. Navigate…
-
Definition of Mortgage — What It Means
Unlock your homeownership dreams! Understand mortgages—secured loans with real estate as…
-
Home Loan Interest Rates in Different Banks: All Banks Compared
Home loan rates at 11 major banks start between 7.00% and 8.50% as of 17 September 2026; Bank of…
-
Home Loan of State Bank of India — Rates, EMI and Eligibility
Dreaming of a home by 2026? SBI offers competitive home loans starting at 7.25% p.a. Discover…